FHA 203(k) Renovation Loans
Buy the ugly house. Turn it into your dream home.
Finance the purchase of a home and eligible renovations through one FHA 203(k) mortgage - and stop paying a premium for someone else's renovation.
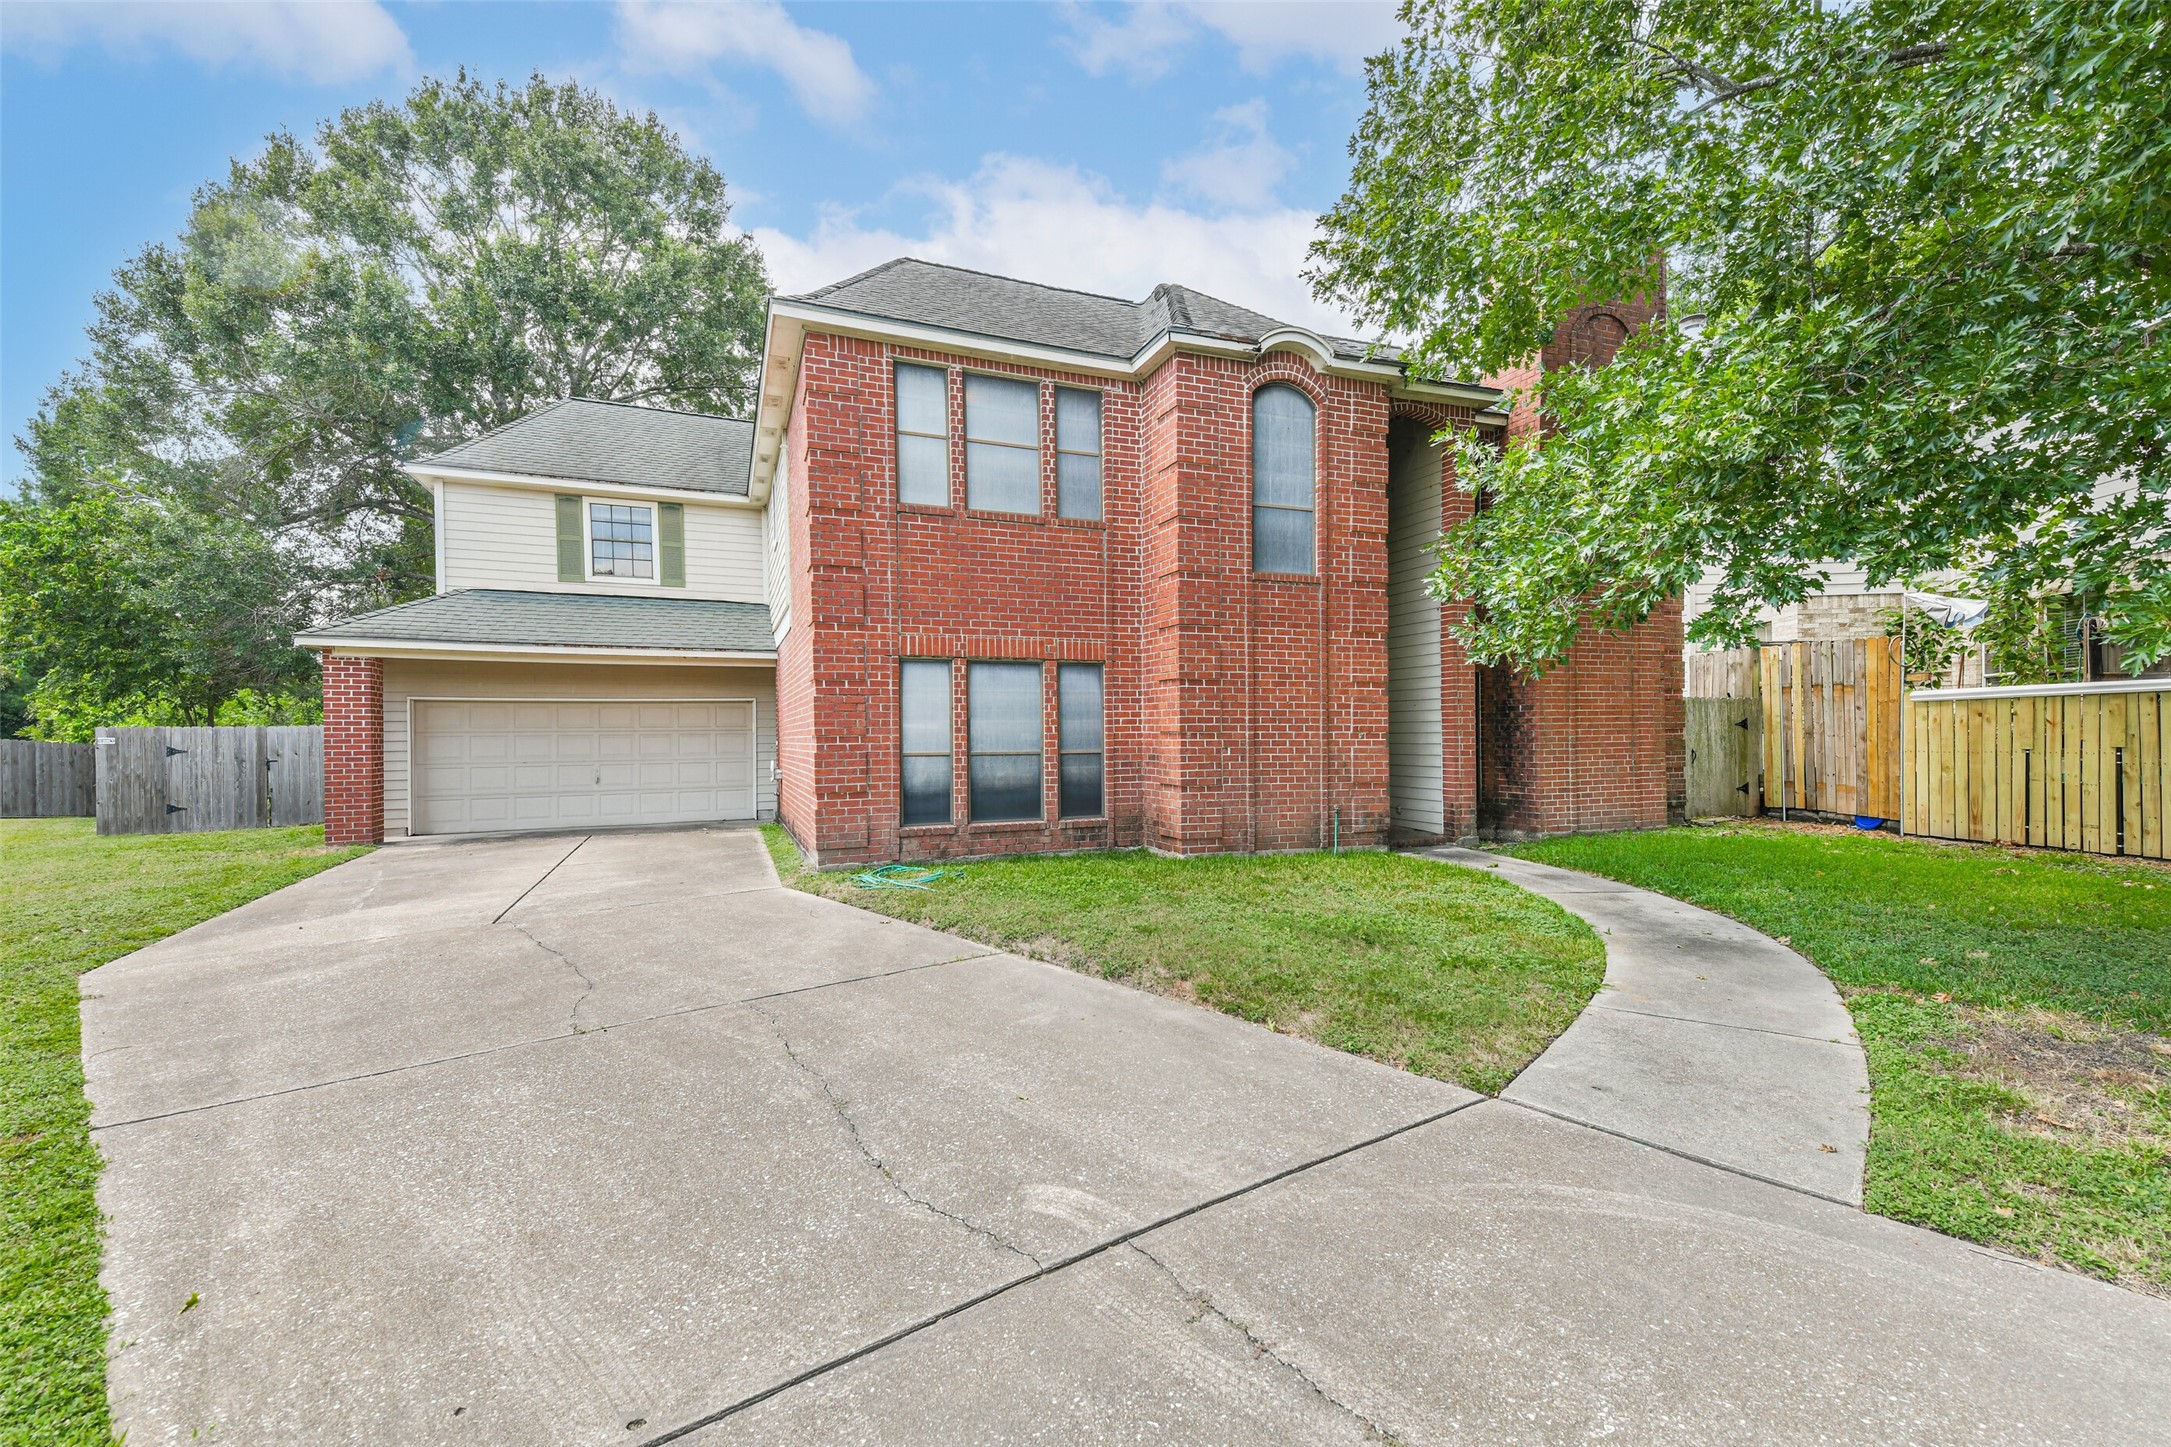 BEFORE
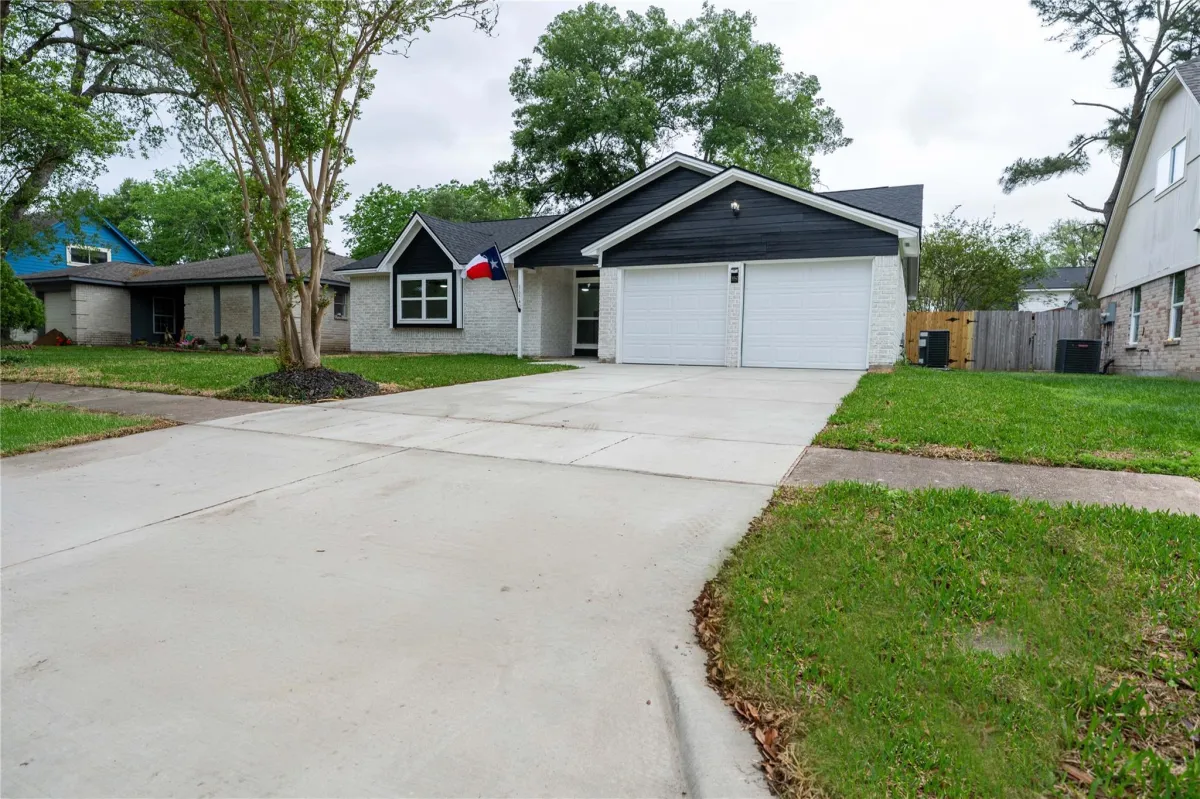
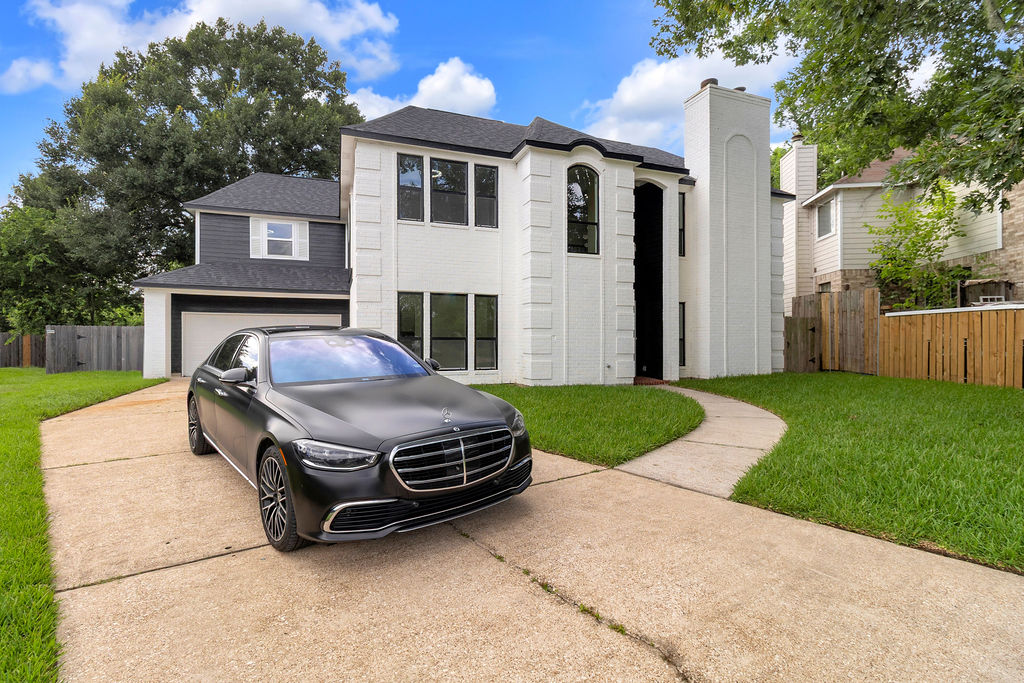 AFTER
FHA-Backed Program
One Mortgage, Purchase + Reno
Licensed Lender
Renovation Funds Escrowed
Licensed Lender
FHA-Backed Program
Renovation Funds Escrowed
One Mortgage, Purchase + Reno
The Case For Renovating Now
A renovation loan isn't a cost. It's a strategy with two returns.
01
Return #1 - Resale & Equity
You build value instead of buying it.
Buyers and appraisers weigh kitchens, baths and finishes heavily. Renovating an outdated home lets you create that value yourself - often for less than the premium a move-in-ready home commands.
02
Return #2 - Daily Life
You get a home designed around you.
Layout, finishes and features chosen by you - not inherited. The return you feel every morning matters just as much as the one that shows up on a closing statement.
Recent Work
Homes, remodeled and made worth more.
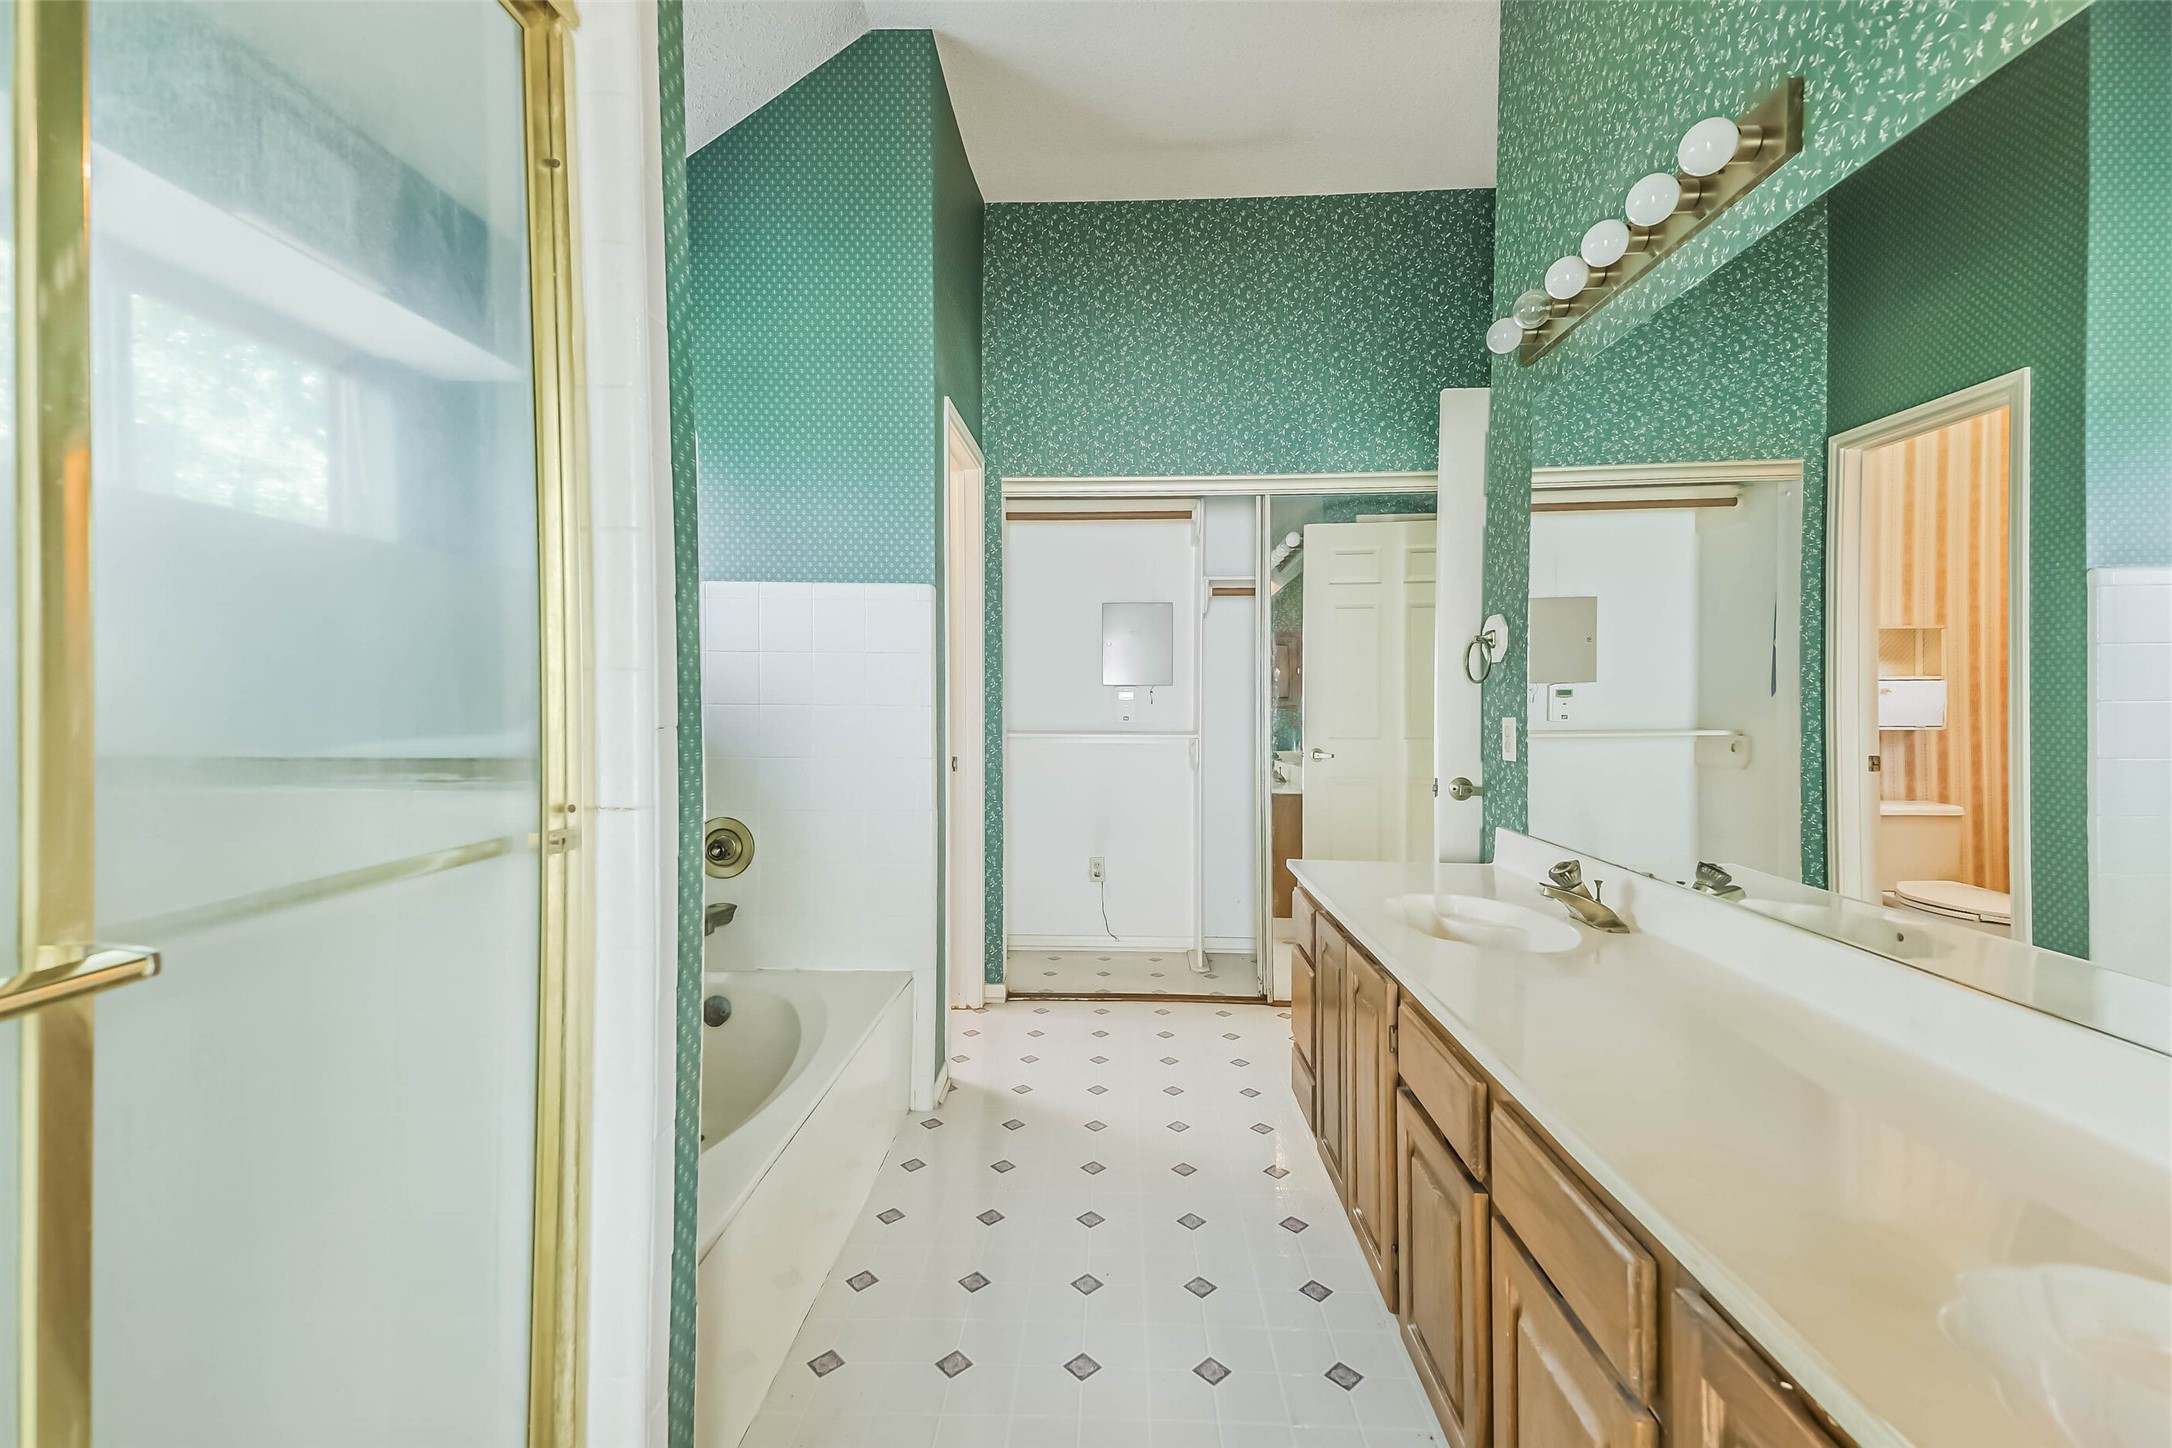 BEFORE
 AFTER
 BEFORE
 AFTER
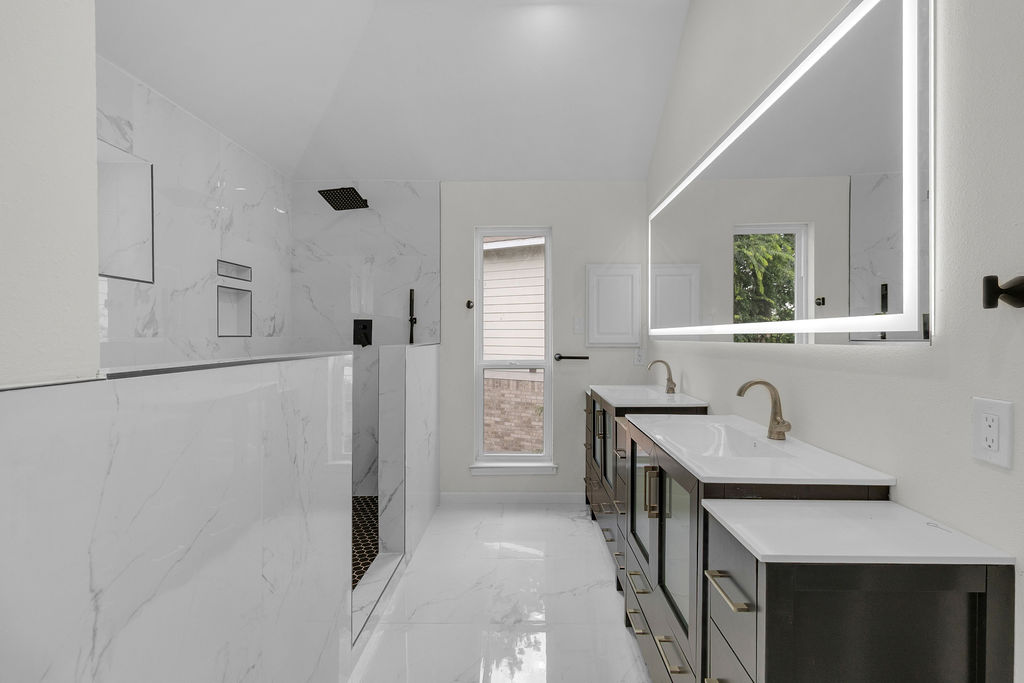
Primary Bathroom
Spa-style rebuild · tile, shower, vanity
BEFORE
AFTER
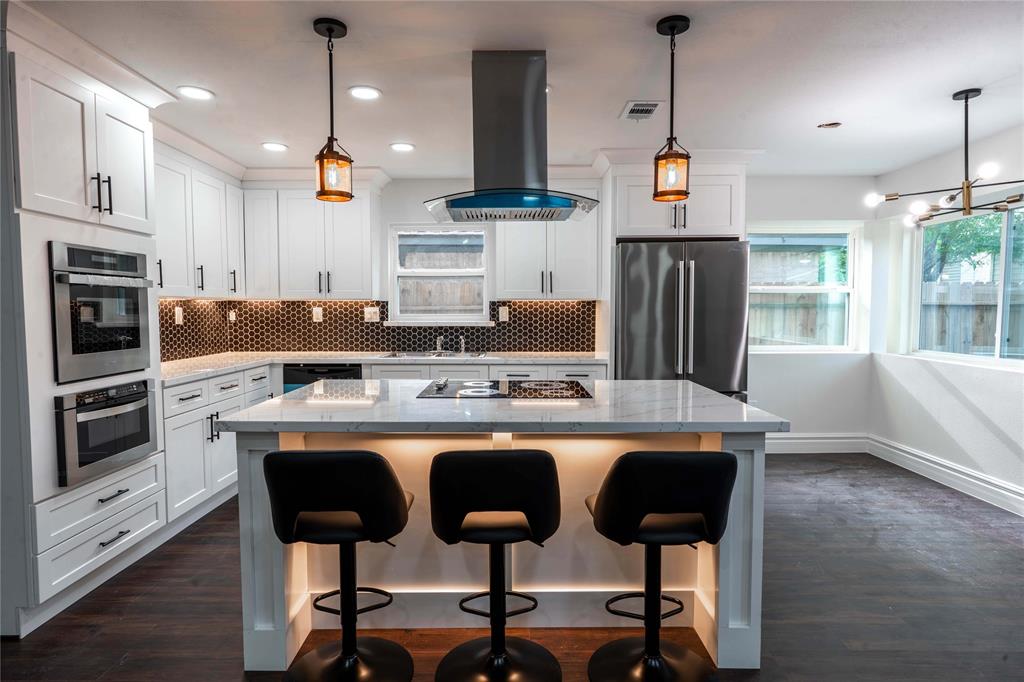
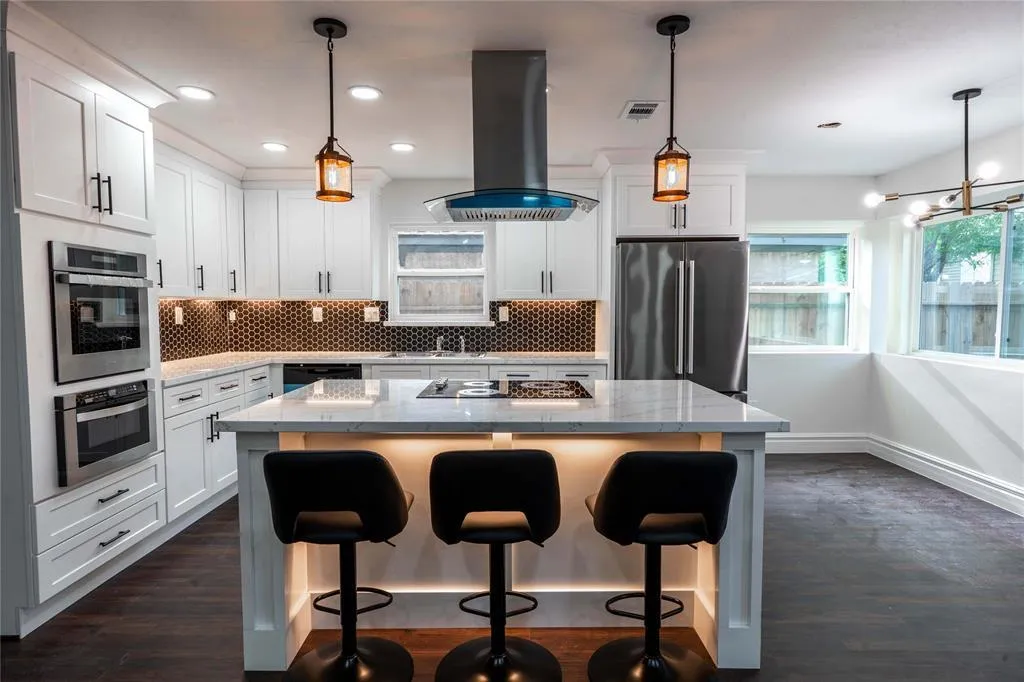
kitchen remodel
Flooring, paint & lighting
 BEFORE
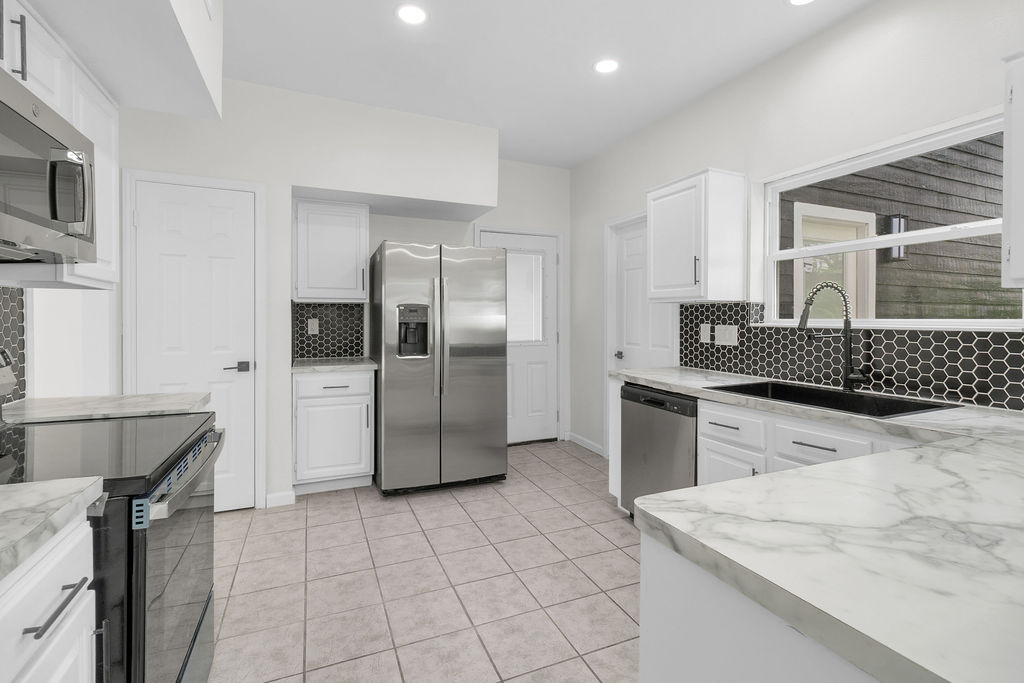 AFTER
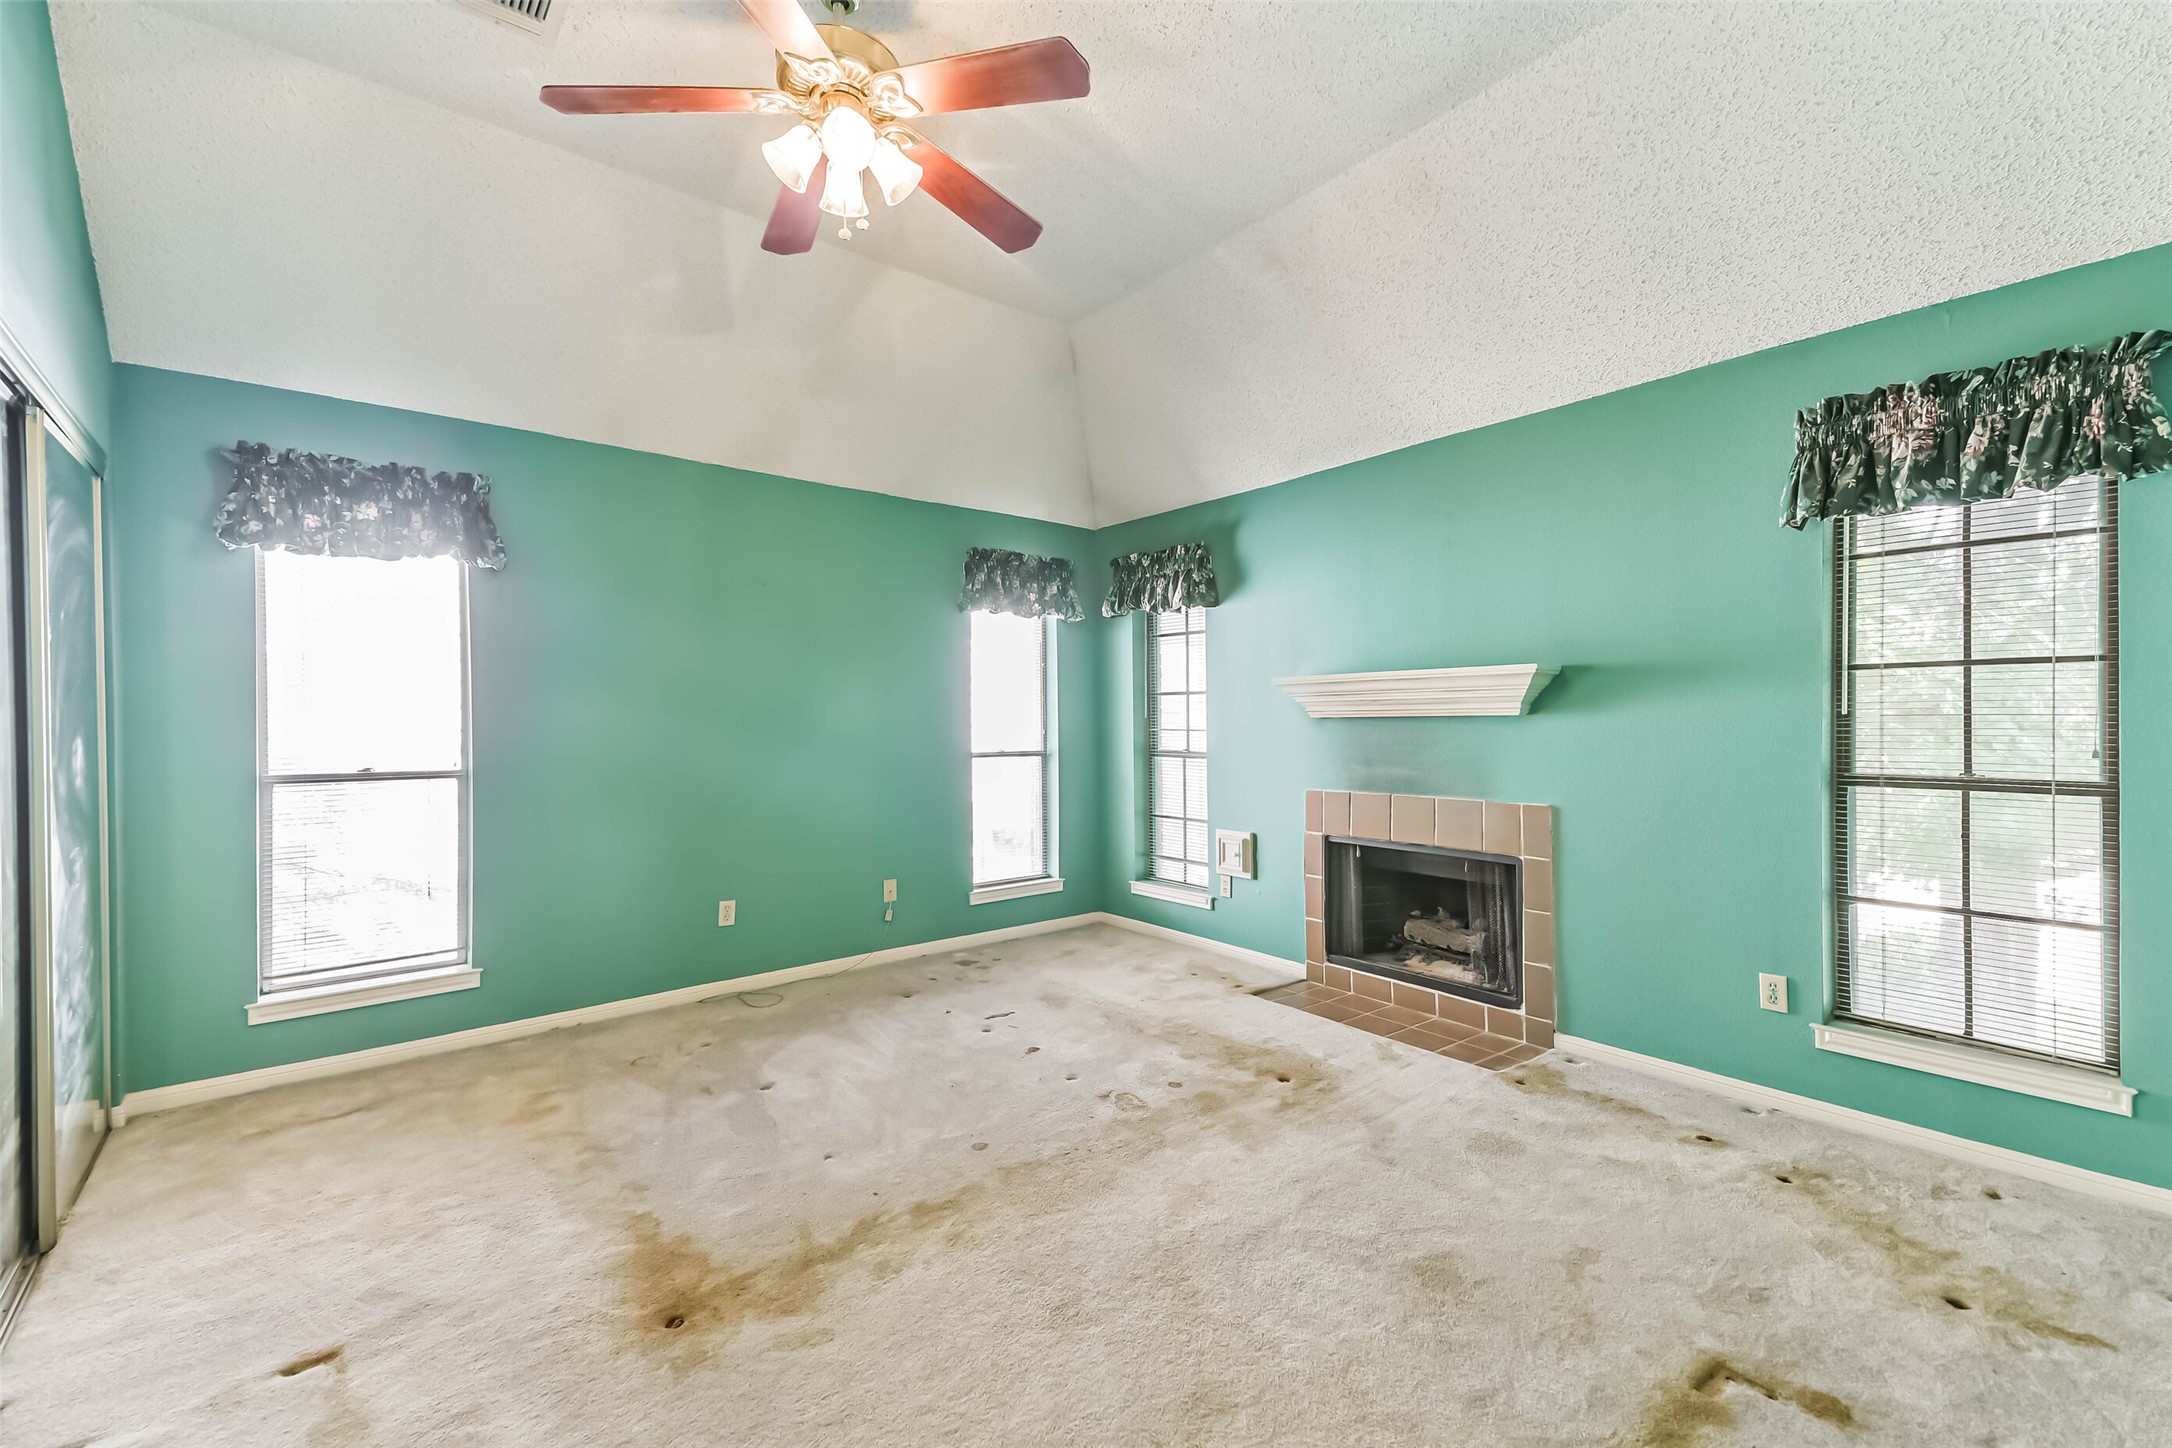 BEFORE
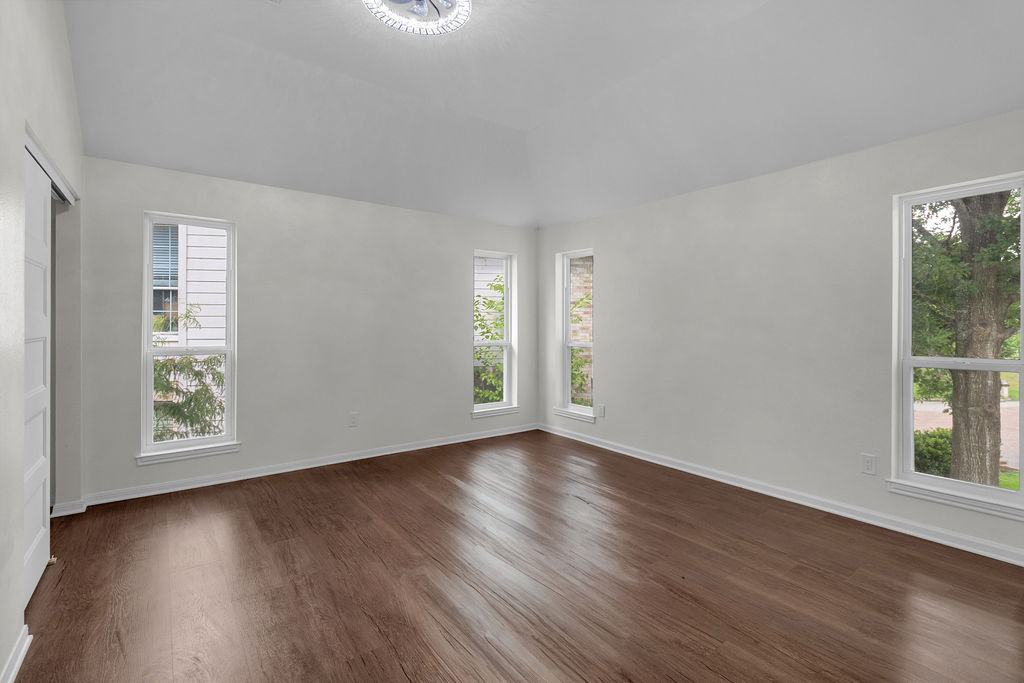 AFTER
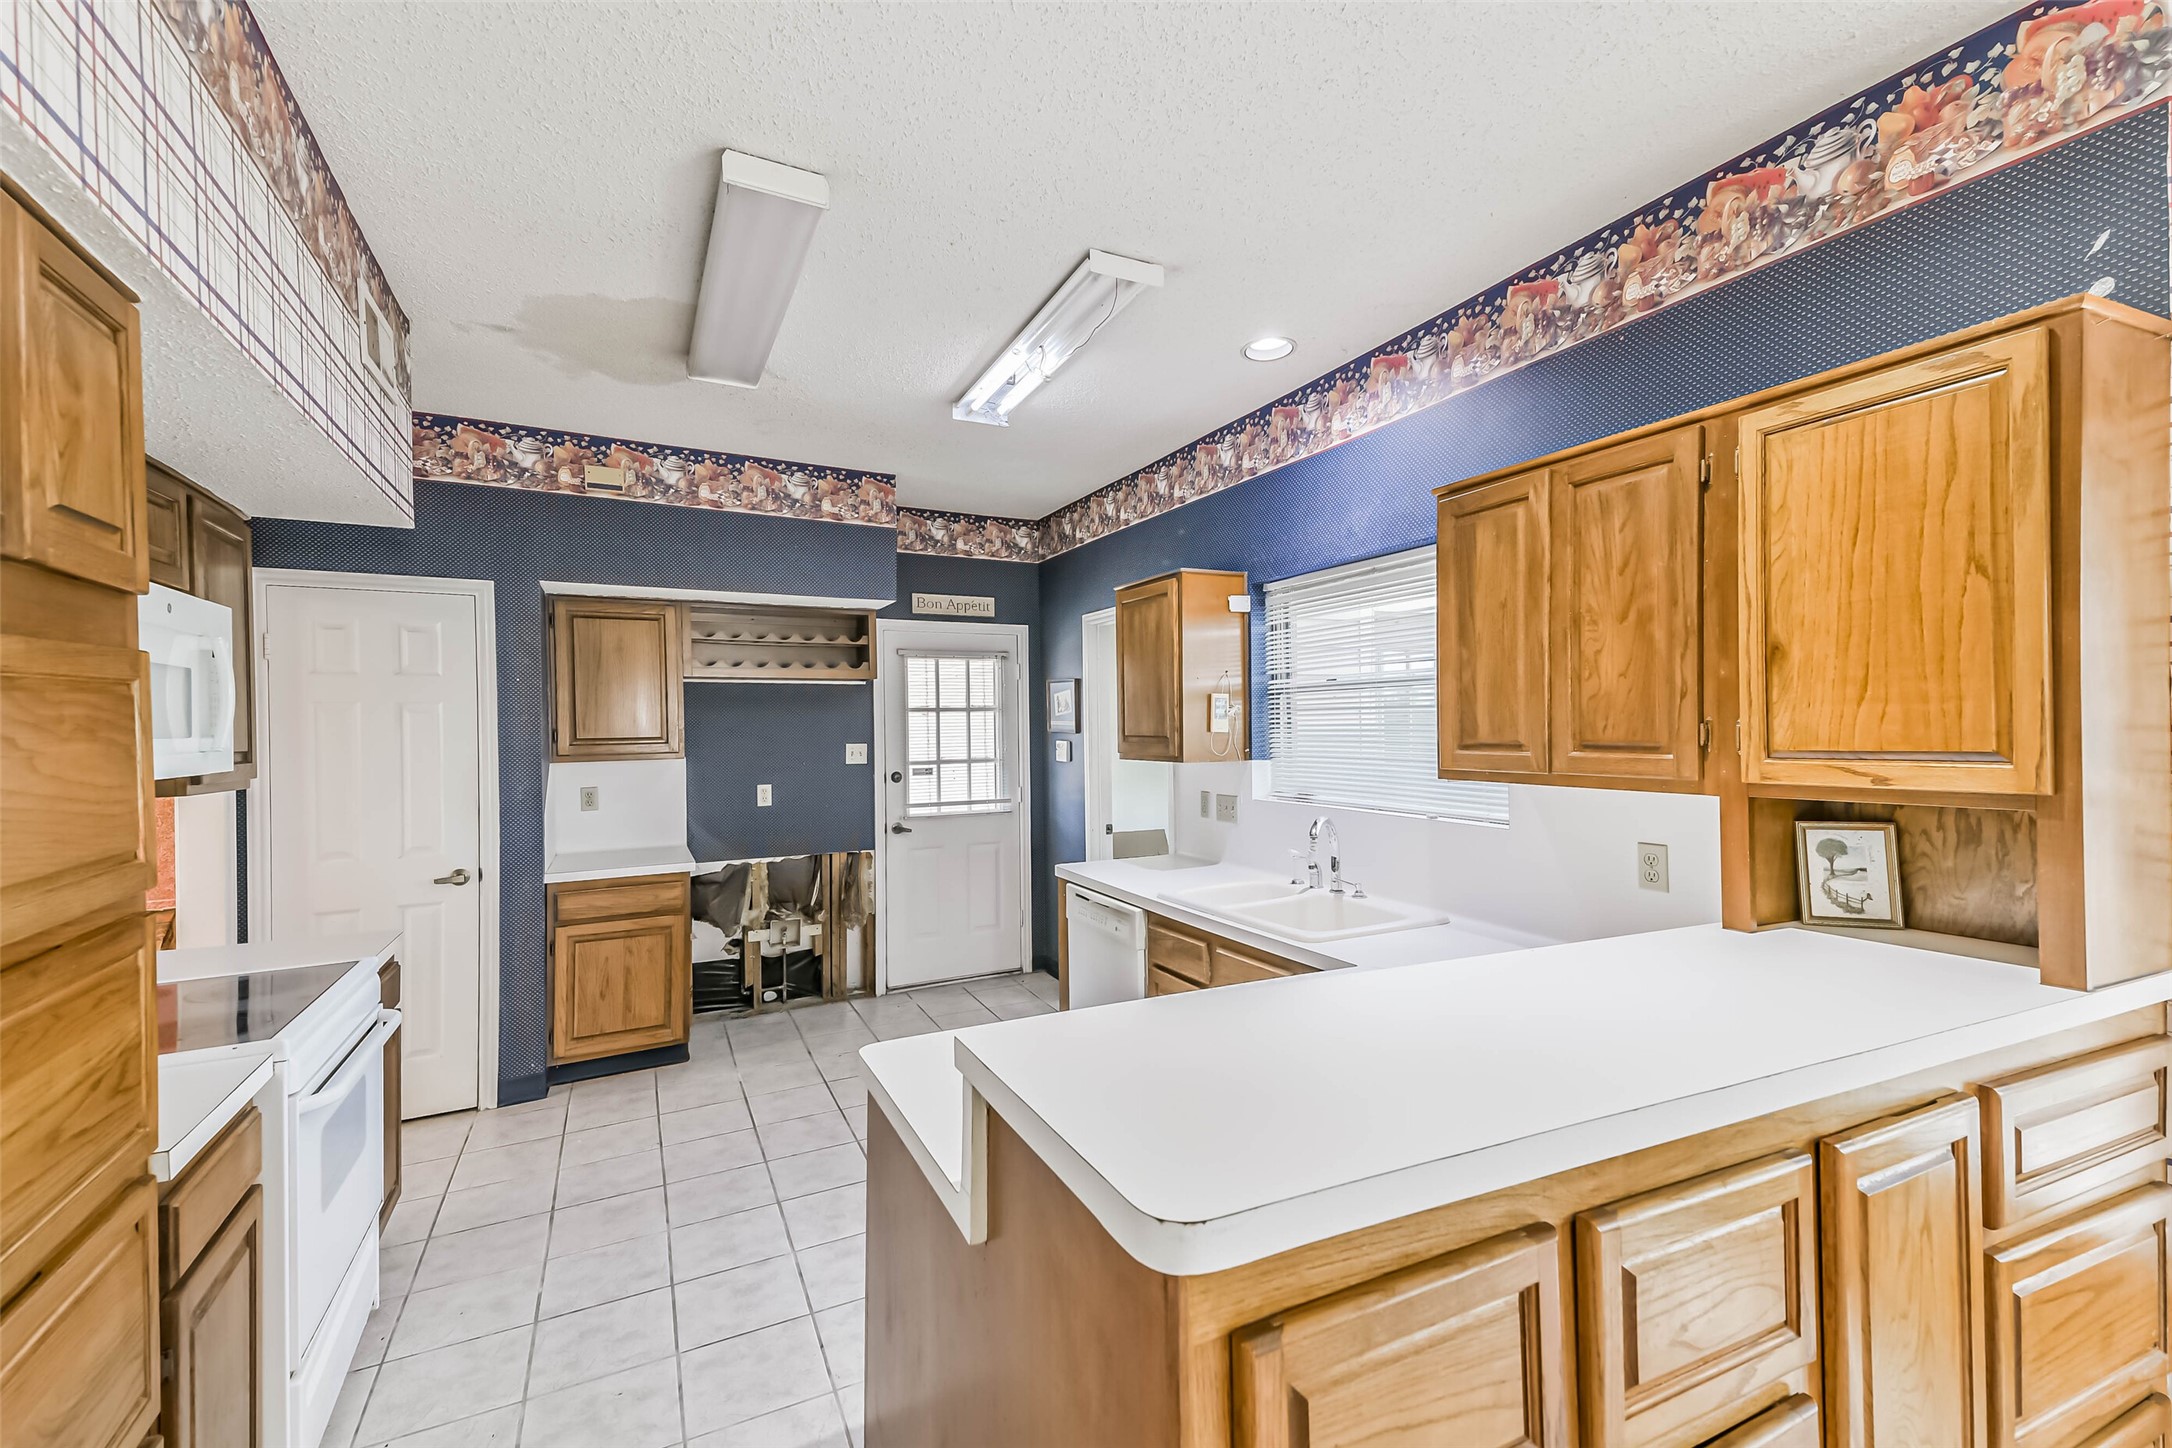
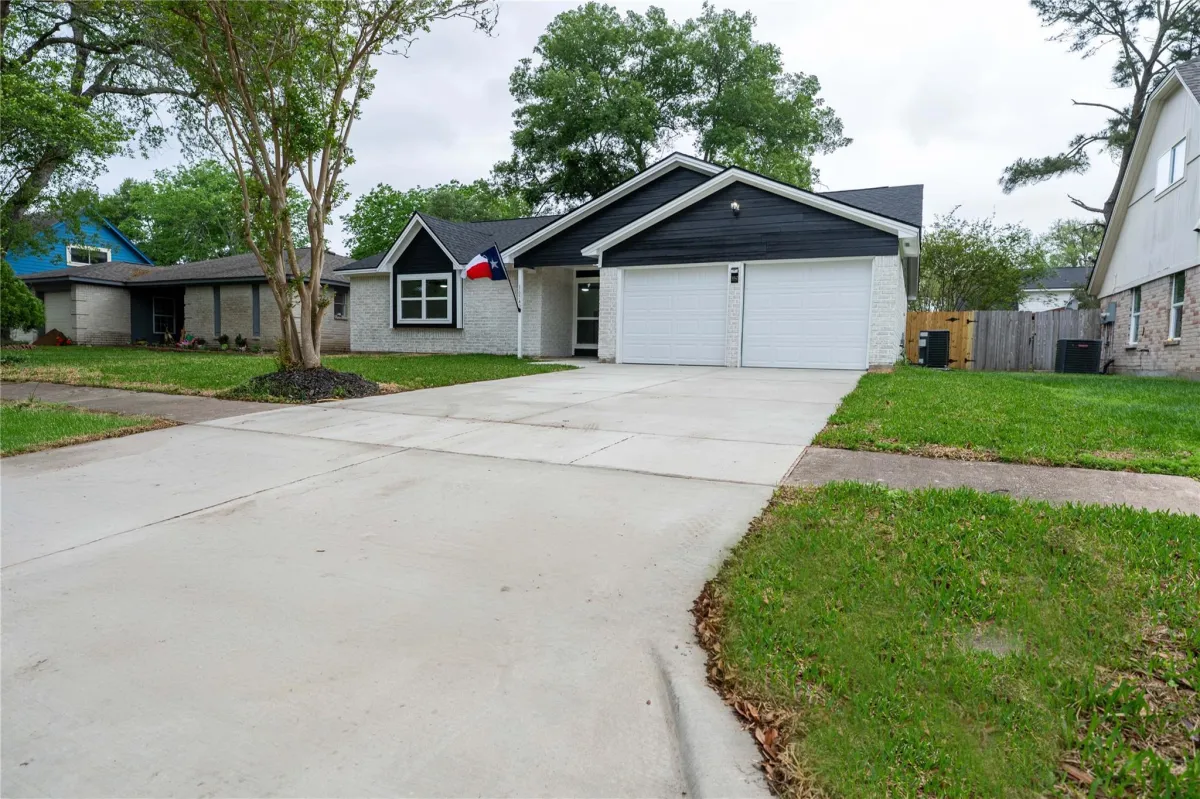
Kitchen renovation
CABEN· Paint, roof, vanity
BEFORE
AFTER
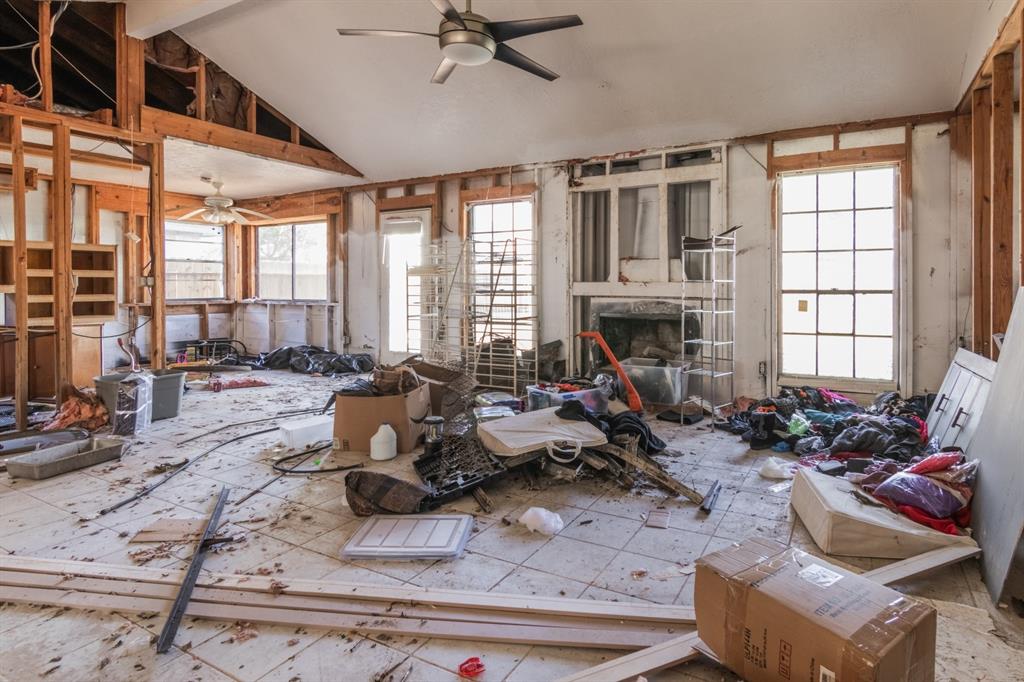
Primary Bedroom
Whole-home finishing touches
Who This Is For
Is an FHA 203(k) the right move for you?
You keep losing out to higher offers on move-in-ready homes
You'd rather renovate to your taste than pay for someone else's flip
You found a fixer-upper but aren't sure how to fund the renovations
You want one loan to cover the purchase and the renovations
You're working with a tight down payment and want FHA options
You want to build equity by adding value, not just buying it
We Help You Build Your Renovation Buying Plan In 5 Simple Steps
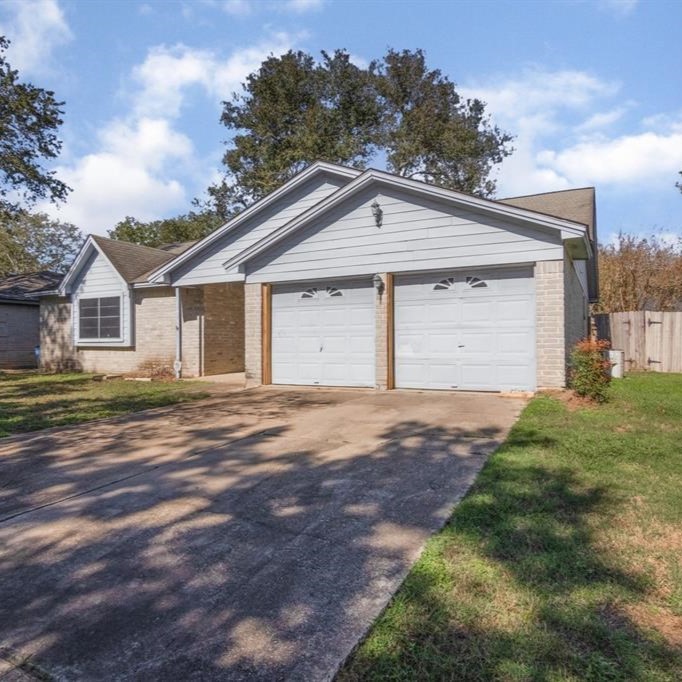
Step 01 of 05
Find the house others pass over
We help you find the worst home in the best community. We create a negotiation stance to help you purchase the property with the best terms. This is where you "make the equity."
Strategic buying and negotiating
A plan you control
Step 02 of 05
Build the financing plan
We can't be strategic negotiators without the funding. Our in-house mortgage team will get you pre-approved so when we find the home you love. This step is critical to ensure our offer is accepted at YOUR terms and at YOUR speed!
We lay out the purchase price & renovation budget
Clear numbers so you're always in control
Step 03 of 05
Purchase Your Home
At this step you are qualified and have identified the home to purchase. We start the process of home inspections, appraisals, title, project management, and shopping for materials (flooring, bathrooms, countertops, roofing, etc.). Yayyyy...shopping!!
One loan: purchase + renovation
Know your numbers througout the entire process
Step 04 of 05
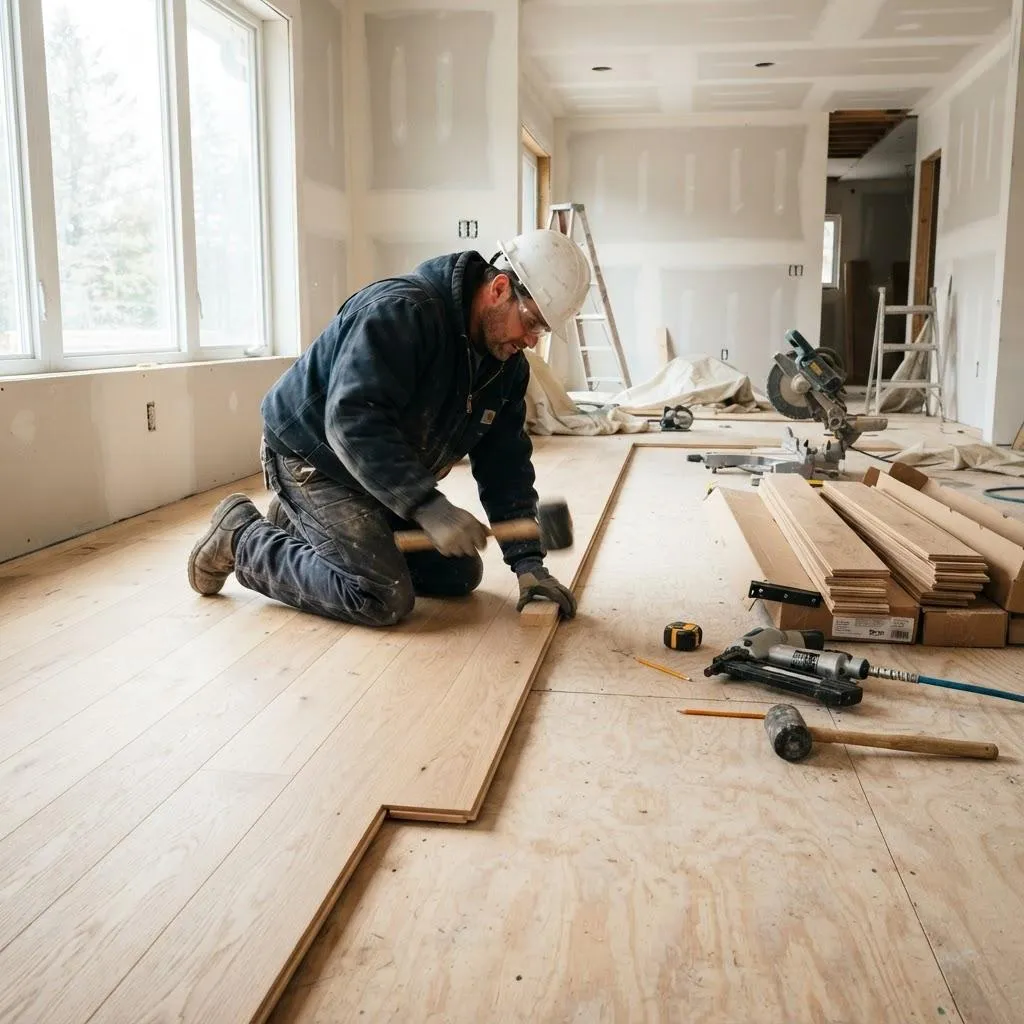
We Start the Heavy Lifting (Literally)
Once we close (buy the home), it's time to start the heavy lifting of bringing your home to life. To ensure compliance, renovation funds are held in escrow and released in draws as work is completed, so improvements stay on track. This ensures that you are never misled or left with an incomplete project!
Funds released as work completes
Completed by licensed contractors
Step 05 of 05
Move into your finished home
You end up with a home built around your vision and equity you created instead of a premium you paid. This sets you in a class of your own when compared to the typical buyer that purchases new construction or a turn-key property.
Equity you created
A home customized for you
Why It Works
Why buyers choose the 203(k) path
One Loan, Not Two
Finance the purchase and the renovations together instead of stacking separate loans.
Escrow-Protected Funds
Renovation money is released in draws as work is completed and inspected.
Equity You Create
Build value through improvements rather than paying a premium for someone else's.
Guidance At Every Step
From property search to closing, you have a clear plan and a point of contact.
Questions
FHA 203(k), explained
What is an FHA 203(k) loan?
An FHA 203(k) is a government-insured mortgage that lets qualified buyers finance a home's purchase and the cost of eligible renovations into a single loan.
What's the difference between Limited and Standard 203(k)?
The Limited 203(k) covers smaller, non-structural renovations with a streamlined process. The Standard 203(k) handles larger, structural projects and involves a 203(k) consultant.
Can I use it if I already found a house?
Yes. If you've found a property that needs work, a 203(k) can finance the purchase plus the renovations you plan.
How are renovation funds handled?
Renovation funds are held in escrow and released in draws as work is completed and inspected, protecting both you and the lender.
Do I have to use an approved contractor?
For most 203(k) projects, work is completed by licensed contractors, and the Standard 203(k) involves a consultant to oversee the process.
Step One
Get your free renovation buying estimate.
Tell us a bit about your goals - we'll walk you through whether an FHA 203(k) fits, and the value it could add, before anything is scheduled.
Helping buyers finance the purchase of a home and eligible renovations through one FHA 203(k) mortgage.
Explore
Get Started
© 2026 Seven Principles Mortgage Group. All Rights Reserved.
Seven Principles Mortgage Group | NMLS #2707217
16420 Park Ten Place, Suite 510, Houston, TX 77084
(877) 287-2700
NMLS Consumer Access: www.nmlsconsumeraccess.org
Equal Housing Opportunity.
Seven Principles Mortgage Group is a licensed mortgage company. All loans are subject to credit approval, underwriting guidelines, income and asset verification, acceptable property appraisal, and applicable state and federal requirements. Loan programs, interest rates, fees, terms, and conditions are subject to change without notice. Not all applicants will qualify. This website is for informational purposes only and does not constitute a commitment to lend.
FHA 203(k) loans are government-insured mortgage programs available through approved lenders. Eligibility, loan limits, and eligible renovations are determined by the lender and program guidelines. This is not a commitment to lend. All borrowers must qualify.